October 12, 2026
The Big Swing: Inside the new golf economy
Happy Monday, everyone. The PGA Tour is off this week, so October goes back to sharing golf with baseball and football.
The LPGA continues its Asian swing at the Buick LPGA Shanghai before the men return next week to Bermuda for the Butterfield Bermuda Championship.
For anyone using the quieter week as an excuse to play rather than watch, that's the right call. There isn't much fall daylight left.

This and that...
DP World Tour tells LIV 2.0 players to choose
Players who sign up for LIV Golf in 2027 will not be allowed to hold DP World Tour membership, BBC Sport reported, closing the route that let some players compete on both circuits this season.
DP World Tour CEO Guy Kinnings told BBC Sport that players now need to “make a choice.” The Tour will not accept membership from players intending to compete in LIV 2.0 and could terminate the membership of anyone who fails to disclose that intention before subsequently playing on the rival circuit, the BBC reported. DP World Tour membership is also required for European Ryder Cup eligibility.
The stance marks a clear change from 2026. In February, the DP World Tour granted conditional releases to eight members to play LIV events on the condition they paid outstanding fines, committed to additional Tour appearances and associated media activity, and withdrew pending appeals. The Tour’s statement said the arrangement applied only to the 2026 season and was not precedent-setting.
The timing adds pressure to LIV’s proposed relaunch. Reuters reported that LIV players have until Oct. 25 to commit to playing in 2027, and that the terms of its restructuring with BC Partners Credit require sufficient player commitments. DP World Tour players have until Nov. 16 to declare their playing intentions for next season. David Puig has already said he will not join LIV 2.0, following Jon Rahm's decision to opt out of the relaunched series.
Our take: LIV 2.0 is trying to assemble enough players to relaunch with a viable field. The DP World Tour has just made that decision materially more expensive. For European players in particular, signing with LIV no longer means balancing two schedules while accepting fines or negotiating releases. It means choosing between LIV and DP World Tour membership, with Ryder Cup eligibility attached to the latter, and Adare Manor less than a year away. The Tour does not have to match LIV financially to compete for players; it can make access to its own ecosystem part of the price of leaving.
PGA Tour backs permanent daylight saving time, citing $1 billion estimate
PGA Tour CEO Brian Rolapp has backed the Sunshine Protection Act, arguing that permanent daylight saving time would provide a significant economic boost to the U.S. golf industry.
In an Oct. 1 letter to President Donald Trump, Rolapp cited National Golf Course Owners Association estimates that keeping an extra hour of evening daylight year-round would generate 23 million additional rounds annually and, in the letter’s words, “$1 billion annually in new direct revenue for the golf industry.” The underlying NGCOA projection, submitted to the Senate Commerce Committee in April 2025, measures green fees at roughly 8,000 public regulation-length courses. It excludes private clubs, cart fees, food and beverage and merchandise. Rolapp also argued that the Tour itself could benefit, with more usable afternoon light giving broadcast partners greater flexibility to finish live coverage and avoid late-round lighting problems.
Not everyone in golf is lobbying alongside the Tour. The American Golf Industry Coalition, whose members include the PGA Tour, the PGA of America and the USGA, “takes no position on H.R. 139, the Sunshine Protection Act, or on whether daylight saving time should be made permanent,” said Greg McLaughlin, CEO of the World Golf Foundation, which houses the coalition. He added that “reasonable people disagree, and we respect that range of views.” McLaughlin has separately argued against permanent standard time, which would move daylight the other way.
The bill passed the House 308-117 on July 14 and has since sat in the Senate Commerce Committee. Two days after Rolapp’s letter, Trump publicly identified Sen. Tom Cotton as the holdout blocking the measure.
Our take: Golf has spent years talking about participation growth, but this is a reminder that one of the industry’s most valuable assets is simply playable time. If the NGCOA estimate is even close, moving an hour of daylight from the morning to the evening creates a meaningful new block of inventory without building a course, adding a bay or selling another club. For operators, that means more tee times. For the Tour, it means a better television window. Few growth ideas come with that little capital expenditure.
Good Good says DTC sales are holding up after retail fallout
Good Good Golf says its direct-to-consumer business has remained resilient despite losing some of its biggest commercial partners following the controversial Callaway driver ad released in August.
The Aug. 21 promotion showed Good Good co-founder Garrett Clark pushing fellow creator Alexis Miestowski to the ground after she reached for the driver in his golf bag. The spot drew widespread criticism, including accusations that it trivialized or endorsed violence against women. By Aug. 27, Callaway had ended its partnership with Good Good, while Dick’s Sporting Goods, Golf Galaxy, Target and PGA TOUR Superstore had pulled merchandise. Good Good also withdrew as title sponsor of the PGA TOUR’s Austin event, while Golf Channel canceled the planned Big Break x Good Good season.
Front Office Sports reports that Good Good’s online store recorded its biggest traffic days ever during the final week of August, according to the company, with two-thirds of buyers first-time customers. A spokesperson said website sales continue to generate “strong, sustained revenue,” particularly in hats, while hundreds of golf-course pro shops continue to carry the brand. Good Good has not disclosed sales figures.
Our take: Good Good’s own account of the past six weeks is unsurprisingly upbeat, and without sales figures it is impossible to know how much business has actually been preserved. What is more interesting is where the surviving revenue is said to be coming from. Losing Callaway and multiple national retailers would cripple a conventional golf brand. Good Good can still reach an audience of more than two million YouTube subscribers directly and sell without asking a retailer for shelf space. That does not make traditional distribution irrelevant, but it is a useful stress test of the creator-commerce model. The national chains dropped the brand, the independent pro shops largely did not, and no retailer ever controlled the audience.
Pro Shop raises $24 million to expand across media, events and commerce
Pro Shop has raised $24 million in Series B funding as it continues to build a golf business spanning media, entertainment, live competition and commerce.
The round was led by Arthur M. Blank Sports and Entertainment, with Causeway Media Partners and Ares Sports, Media and Entertainment funds joining as new investors. Returning investors included the PGA TOUR, Powerhouse Capital and Phoenix Capital Ventures. Pro Shop says the capital will support further investment in digital media, original programming, talent-led franchises, live events and competition formats, commerce and strategic growth. Its portfolio includes Full Swing, Creator Classic, The Skins Game, GolfWRX, Sugarloaf Social Club and Paige Co.
Our take: Pro Shop increasingly looks less like a golf media company than a business built around owning golf attention wherever it appears. A documentary, a creator event, an editorial property and a commerce brand are very different products, but they can all feed the same audience. The $24 million question is whether that audience can be moved profitably between content, live competition and commerce. If it can, Pro Shop is building something closer to a golf holding company than another publisher.
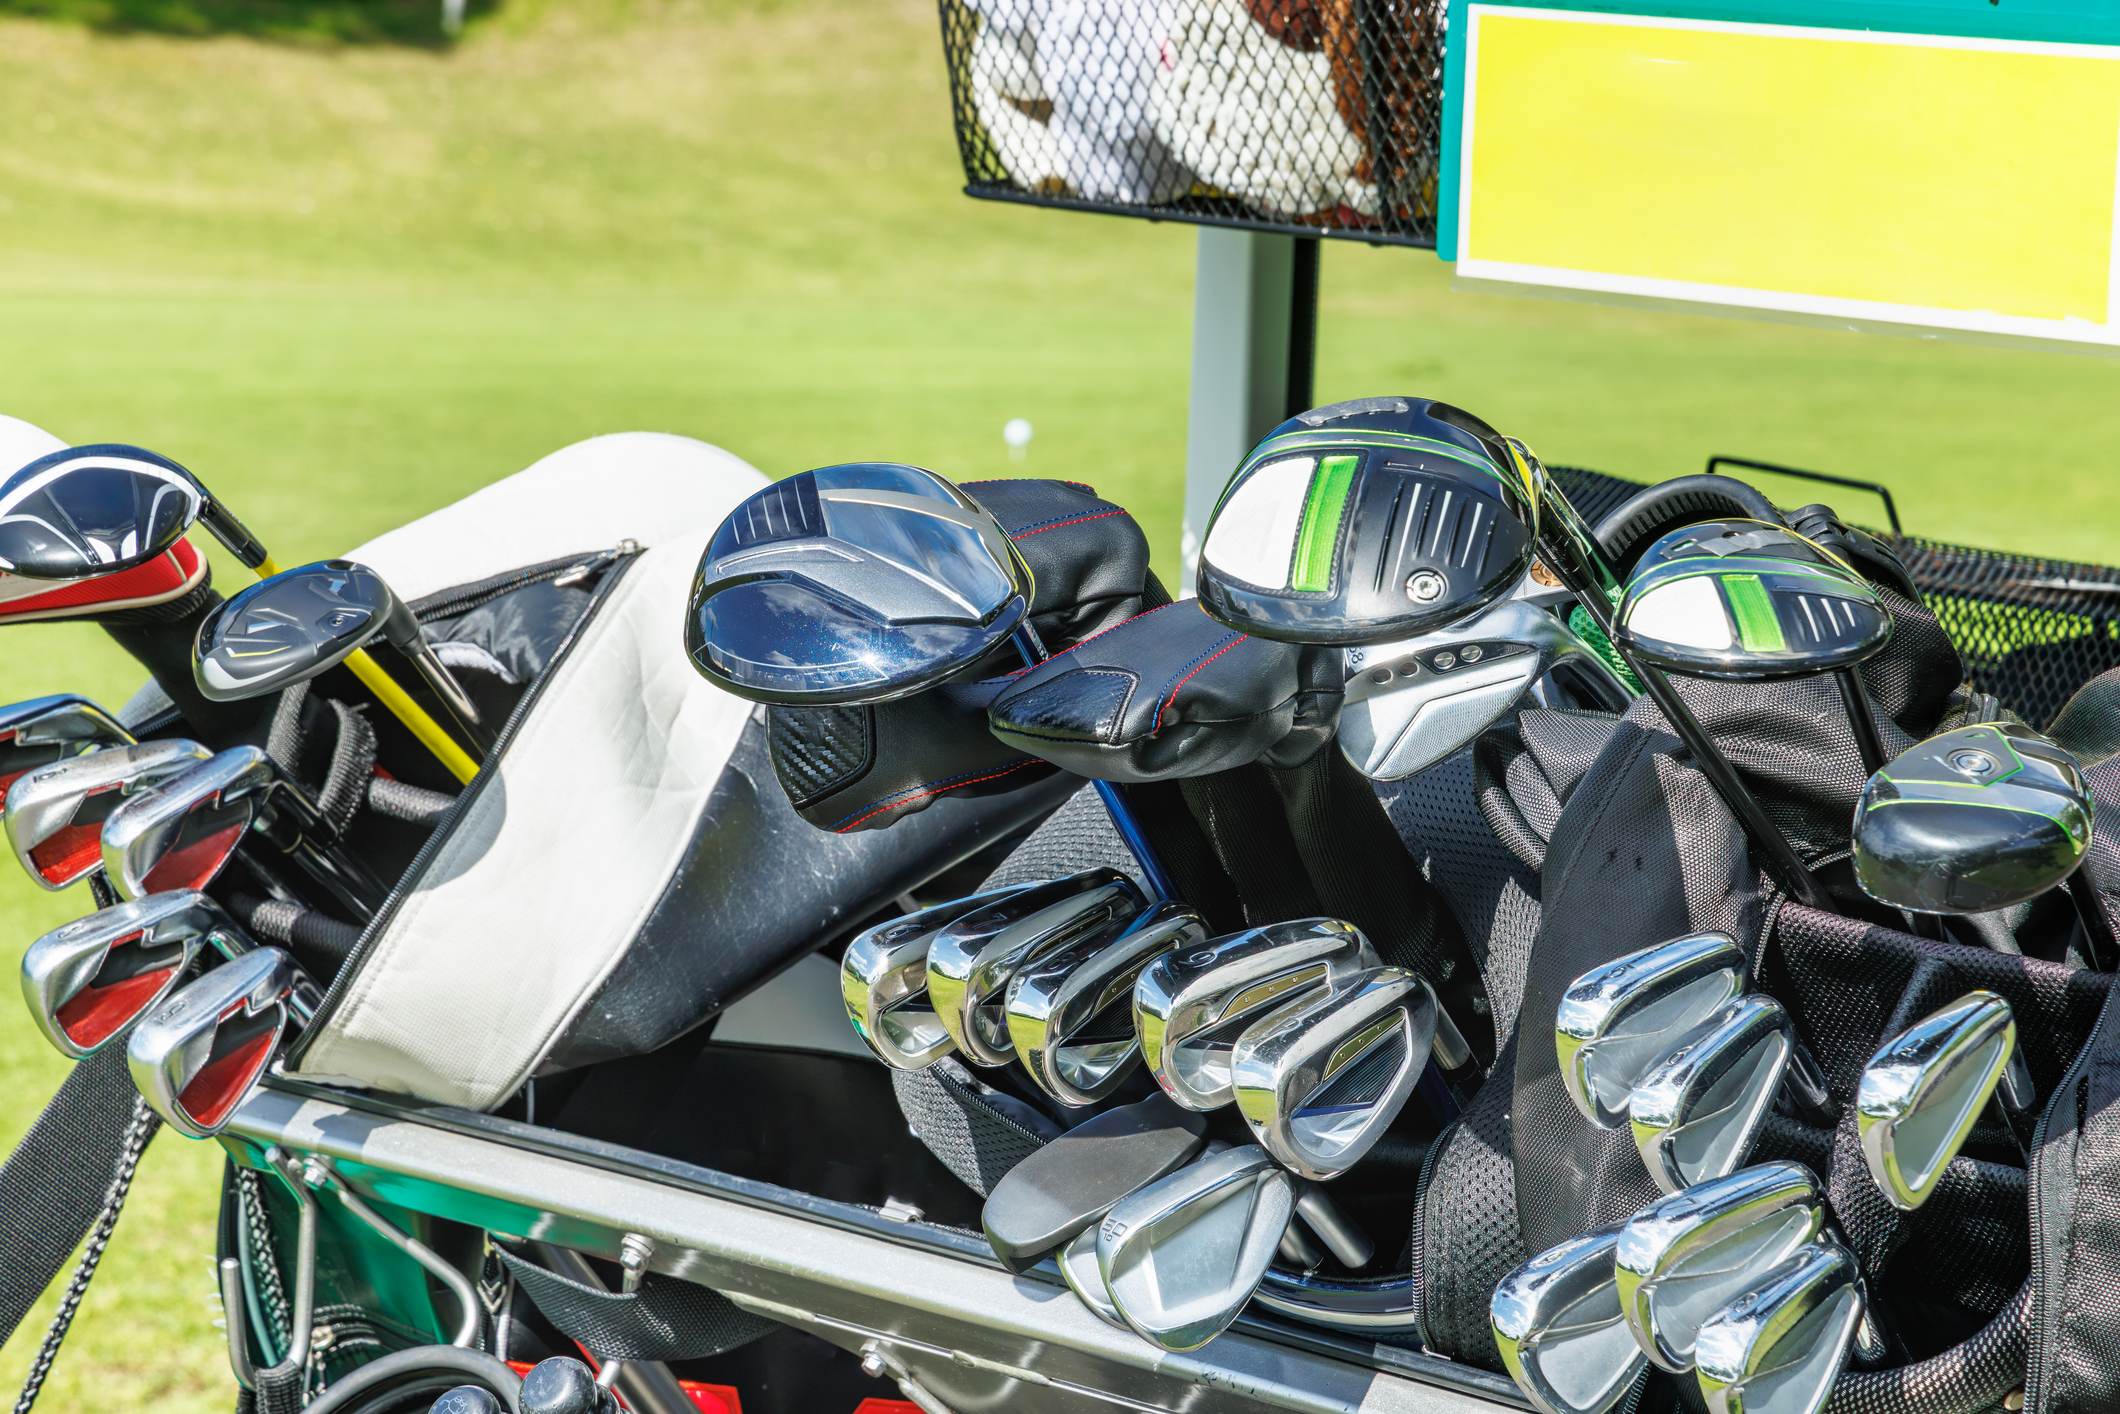
Golf's DTC Brands Cut Out The Shop. Now They're Rebuilding it.
Golf’s direct-to-consumer brands once promised to cut out traditional retail and deliver better value straight to golfers. Now, some are rethinking that approach by investing in fitting, demos and in-person experiences, revealing why even the most digitally driven brands may need a place in the pro shop.
October 12, 2026
Gianni Magliocco | gianni@bigswingmedia.news
A golfer orders a new set of irons directly from a brand without a traditional dealer network. The clubs are built to spec, shipped to his door and never pass through a golf shop. That is the direct-to-consumer model in a nutshell.
For much of the industry, that is a very different transaction from the one it was built to measure and monetize.
Direct-to-consumer golf brands are no longer simply selling cheaper clubs online. Companies such as Sub 70 and Takomo now offer custom-build options, fitting tools, demo or trial programs and direct customer support, recreating parts of the infrastructure that once made traditional retail indispensable.
That creates a three-way tension.
DTC brands are trying to own the golfer relationship from first click to final sale. Established OEMs see the attraction of that model but still depend heavily on retailers to move volume. And retailers increasingly find themselves competing against brands that can bypass the store entirely.
A parallel equipment market is growing alongside traditional retail. The harder question is how large it has become, and whether industry data can capture it.
The Margin the Model Removes
The appeal of direct-to-consumer is simple: remove the retailer, and more of the selling price remains to be split between the brand and the golfer.
Jason Hiland, Sub 70’s founder and chief executive, describes the savings in structural terms rather than financial ones. “We don’t have sales reps,” he said, and “the old system is like a 1950s distribution model. We just want to be in a different, more modern lane.”
He would not put a figure on what that saves, calling those internal numbers, and he was clear the comparison is inference rather than measurement: having never worked at a TaylorMade, he would “have to imagine” his chain is shorter.
Sub 70’s direct-to-consumer page says most major companies sell through a dealer network that “marks that product up 40 to 50 percent” before the club reaches the golfer. On a $600 driver, that implies the shop paid roughly $400 to $430 and kept $170 to $200 before staff, fittings, rent, inventory and markdowns. Measured the way retailers measure it, that is a gross margin of 29 to 33 percent. Published summaries of Circana’s 2025 membership study for the Association of Golf Merchandisers, covering fiscal 2024, put the average gross margin at member shops at 35.8 percent. That figure covers all merchandise rather than drivers and skews toward private clubs, but it puts Sub 70’s estimate in broadly the same range.
A direct brand does not simply pocket the retailer’s share. By removing the shop, it takes on customer acquisition, fitting support, demonstrations, shipping, returns, warranties and service. It gains control: it can pass some of that margin to the golfer, keep more of it, or spend it rebuilding what retail used to provide. DTC does not eliminate the cost of selling a golf club. It relocates it.
The Blind Spot
The difficult part of assessing direct-to-consumer golf is working out how much of it the industry can actually see.
Golf Datatech’s monthly retail tracking draws on a panel of point-of-sale systems across on-course shops, off-course specialty retailers and e-commerce channels. That makes it an important measure of what is moving through established golf retail. But a club bought directly from a manufacturer does not necessarily pass through any of those systems.
The channel is not invisible. Golf Datatech, now a Circana company, surveys golfers directly about where they buy, and its 2025 Serious Golfer study lists purchasing channels including custom fit specialists, online golf retailers and “direct to consumer (from OEM).”
That last category is the one that matters, and it is ambiguous. Direct from an OEM could mean a driver bought on TaylorMade’s website or a set of Sub 70 irons. Those are very different businesses, and the distinction decides how much of the direct channel the numbers actually describe.
Circana did not respond to questions about whether manufacturer-direct sales from DTC-native brands are reflected in its monthly brand and category share reporting, or whether unobserved transactions are modeled.
If a meaningful share of DTC sales falls outside the core monthly retail data, the published numbers may not be wrong. Instead, they may describe the measured retail market rather than the entire equipment market.
For an industry accustomed to quoting market share to the decimal point, that is a meaningful blind spot. That is also why no authoritative public figure appears to isolate how much golf equipment DTC-native brands sell.
The Middleman Returns
Ironically, as direct-to-consumer brands have grown, some have started rebuilding the very infrastructure their model was designed to remove.
Sub 70 now offers fittings at The Seventy in Sycamore, Illinois, which the company says is open by appointment only. It also runs a network of fitting-cart partners, while golfers farther away can use the company’s demo program for $20.
The company says it builds all clubs to order in Sycamore, while its trade program currently routes customers through Golf Stix Value Guide rather than being handled entirely in-house.
Hiland is explicit that the fitting network costs Sub 70 margin, because the fitters have to make money too. “We’ve definitely discounted the product down enough so the fitters make a profit,” he said. “We definitely take a little bit of a haircut for sure to let those guys work with our product.”
That is the retailer’s share reappearing inside a model built to remove it. Sub 70’s own direct-to-consumer page says flatly that “there are no ‘dealer’ markups.” Hiland describes the fitting partners as non-traditional retail rather than dealers, but a third party is taking a margin either way. The demo program works the same way. “No, we lose money on it,” Hiland said. “It’s a net loser from that standpoint.”
Returns are where the model meets the golfer most directly. Sub 70’s direct-to-consumer page promises a “100% money back guarantee.” Its published return policy gives a 30-day window to start a return, states that “all returns are subject to a 10% restocking fee,” and makes the customer responsible for shipping the clubs back to Sycamore. Refunds are issued minus the fee; on a $600 club, that is $60 to change your mind, plus the freight.
Hiland described it differently, saying the company refunds in full inside 30 days and applies the fee after that. The published policy makes no such distinction and offers no route to return a club once the window closes. He was clear the written terms are a floor: “We have to have rules,” he said, but “if someone’s willing to work with us, we are more than happy to do everything we can to make sure the product is right.” The policy page likewise encourages customers to call before starting a return.
Both of those can be true at once. But the written terms are what a golfer reads before buying, and a published 10 percent fee differs from one waived on request.
Hiland rejects the idea that any of this makes Sub 70 a retailer. He says the company has turned down more conventional opportunities and will not be “in 80 different locations,” and he draws the line at the big-box floor. “I think it would become blurred if we were in PGA Superstore or something like that,” he said. “If the clubs were just in there, it would be blurred.” At a Sub 70 fitting partner, “you can’t just go buy a golf club off the rack, you have to go get fit for it.”
The question is how much retail a direct brand can rebuild before the economics that made direct selling attractive begin to disappear.
Why the Incumbents Can’t Go All the Way
Established manufacturers have already adopted parts of the DTC model. TaylorMade sells customized drivers through its own website. Callaway does the same, alongside its own rewards and trade-in programs.
The problem is not whether they can sell direct. The question is how much business they can move there without damaging the distribution network that made them large in the first place.
Callaway’s Form 10-K for the fiscal year ended December 31, 2025, shows how significant those relationships remain. Its five largest golf equipment customers accounted for approximately 24 percent of consolidated golf equipment sales, against 26 percent in 2024. The company warns that consolidation can give larger retailers increased leverage, and that if one “substantially reduces their purchases of our products, we may be unable to find a sufficient number of other retail outlets for our products to sustain the same level of sales.”
Those retailers do more than process transactions. They hold inventory, provide fitting, give launches physical visibility and let golfers compare competing products in the same room. PGA TOUR Superstore’s Fit & Go program, for example, fits and assembles selected drivers the same day.
That creates the incumbent’s dilemma. Every sale moved to an OEM’s own website can deliver better economics and a more direct customer relationship. Push too far, however, and the manufacturer is competing more aggressively with businesses it still needs to sell its products.
Sub 70 had no legacy distribution channel to protect when it went direct.
The incumbents do.
What Direct Still Can’t Do
The direct model solves one problem particularly well: price. It does not automatically solve trust.
Golf remains unusually dependent on validation from elite players, and Takomo has broken through by a different route. Three new owners emerged in the space of five days in January 2025. Grant Horvat, a YouTube creator with close to a million subscribers, announced on Jan. 4 that he was “officially an owner of Takomo Golf.” Five days later Golf Monthly reported that PGA TOUR winner Wesley Bryan, who plays Takomo irons in competition, and his brother George had joined him as shareholders. Takomo says the Bryans have since collaborated on its wedge development.
That is a different currency. Traditional equipment companies have long built credibility through tour contracts and widespread retail visibility. Takomo is building some of the same trust through ownership, giving creators and players a direct financial stake in the brand they promote. The order is revealing: Horvat, with the larger digital audience, came first, and the Bryans followed five days later with both creator reach and a PGA TOUR win behind them.
The resource gap is real but unquantifiable. Callaway spent $65.5 million on company-wide research and development in 2025, and Acushnet $76.5 million. Private DTC companies do not publicly disclose directly comparable R&D figures.
Resale is another place the data thins out. 2nd Swing currently stocks used Sub 70 equipment, so direct brands are not shut out of the secondary market, but no benchmark shows how they hold value as a group against the major OEMs.
Then there is the most concrete friction. Under Sub 70’s written policy, changing your mind means shipping the club back at your own cost and losing 10 percent of the purchase price.
Buying direct can cost less. Changing your mind costs more.
Who’s Exposed
The immediate threat from direct-to-consumer may not be to TaylorMade, Callaway or Titleist. It may be to the retailers sitting between them and the golfer.
The largest manufacturers can play both channels, with the recognition and resources DTC brands are still building.
The strongest retailers have their own defenses. 2nd Swing combines new and used inventory with fittings, trade-ins and club building. Acushnet’s Form 10-K for the fiscal year ended December 31, 2025, describes retail partners as “a critical connection to dedicated golfers.”
The more exposed retailer is the one in the middle: carrying inventory and absorbing the costs of a physical store without adding enough expertise, convenience or service to justify the margin between manufacturer and golfer.
Direct selling does not need to replace the best fitter or the biggest retailer. It only has to persuade enough golfers that the intermediary is optional.
If part of the shift happens outside the retail data used to judge the market, businesses losing those sales may only grasp the change when it hits their own tills.
The unanswered question is no longer whether a direct golf-equipment market exists.
It is how large it already is.

One last thing... Jimmy Roberts
Paws and Perspective
Not sure this makes any sense … but we just got a dog. Let me be specific—we just got ANOTHER dog.
But really, the most significant part of this revelation is that we just got a PUPPY.
In the bleary-eyed middle of the night, when she’s yelping to go out, I’m painfully aware that THEORETICALLY, this might have seemed like a good idea … in reality, though, I’m left with an obvious and undeniable question:
What the hell were we thinking?
But then you wake up in the morning, and this is the face that greets you—this is Bella, and this is her pal Buddy—and it makes perfect sense, even if it doesn’t.
I’m not here to hate on cats, although I’m allergic to them. I liken the way I feel about people who have cats to the way we all feel about people who vote differently than we do … whatever that might be … I just don’t get it.
God bless you if you have a turtle or an armadillo or a hamster …
Dogs are—and I mean this literally—better than people. They are SO much better. If you know, you know.
OK, so now that you know where I stand on the issue, can we talk for a minute about the other side of this issue?
Too many dog-people seem to have lost their minds.
They drive with them on their laps—more on that in a minute. They bring them to restaurants and supermarkets. I was at dinner the other night, and a lady had her dachshund sitting in a chair next to her! In a chair! Forget about the fact that she was feeding Fido off her plate; it clearly didn’t occur to her that the next person at that table might not have wanted to be sitting on a chair previously occupied by Lassie … whose paws had been God only knows where!
Back to the driving thing: These people who drive with lap dogs literally on their laps.
So what happens if, while you’re piloting a 3,000-lb. hunk of iron around at 45 miles an hour … THROUGH A SCHOOL ZONE, your little cutie decides to relieve itself … or maybe tries to jump out the window at a squirrel? A little distracting, perhaps?
Dogs are great—as the T-shirt says, we don’t deserve them. And anyone who’s lost one understands how deeply embedded in our souls they are …
But—and this is to all my dog-loving brothers and sisters out there—can we please just understand they are NOT people? Doesn’t mean we should love them any less … what it does mean is we’ve gotta come to our senses.
Past Briefs
Monthly and Annual Membership Options Available.
Member Pricing
$9.99 per month, OR $99 for one year.
Cancel Anytime.
Available for a limited time only, subscribe to our twice-weekly Golf Business Intelligence Brief for a discounted rate of $9.99/month or $99/year. Subscription renews at the same price each month or year, depending on the subscription selected.
Purchase Disclosure
By completing your purchase, you agree to enroll in a monthly or annual subscription to The Big Swing Golf Business Intelligence Brief at the current rate of $9.99 a month or $99 a year.Your subscription will automatically renew monthly at $9.99 or annually at $99 unless canceled prior to the renewal date.
You may cancel at any time through your account settings or by contacting customer support. All sales are final and non-refundable except where required by law.
Offer valid for a limited time and may not be combined with other promotions. Limit one per customer.
By subscribing, you agree to our Terms of Service and Subscription Terms.