September 28, 2026
The Big Swing: Inside the new golf economy
Are you not entertained?
The U.S. completed the biggest final-day comeback in Presidents Cup history to win 17-13 at Medinah for its 11th consecutive Presidents Cup.
The PGA Tour, NBC and all tournament sponsors couldn’t have asked for a better event as the Tour gets set to usher in its new era under Brian Rolapp.

This and that...
A $1,750 putter, a Curry collaboration, and a sold-out first model
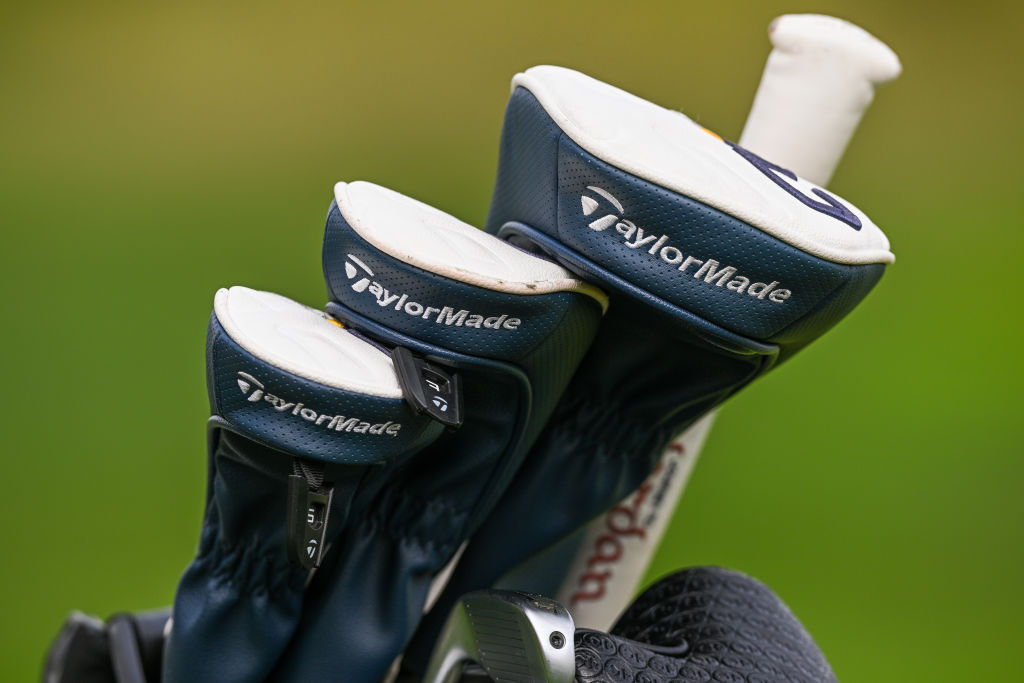
L.A.B. Golf has launched a limited-edition collection with Stephen Curry’s Underrated Golf Tour, priced at $1,750 per package. Custom versions of the VZN.1i and OZ.1i each include the putter, a co-branded headcover, an accessory pack with a divot tool and ball marker, and a custom Underrated box. The VZN.1i is already listed as sold out. L.A.B.’s product and collection pages do not disclose the size of the production run, and all Underrated x L.A.B. products are sold without returns, cancellations or order changes. L.A.B. is the official putter of Underrated Golf Tour and provides onsite fittings and custom-built putters for participants at the tour’s five annual U.S. competitions. The company says a portion of the proceeds from every Underrated x L.A.B. putter sold goes back to the junior tour.
Our take: At $1,750, L.A.B. isn’t just selling a premium putter; it is packaging its technology with Stephen Curry’s brand, a limited-edition design and a cause. One model already selling out at that price suggests an audience for the combination. The deal shows how an equipment company can turn an athlete partnership into something more tangible than awareness or endorsement: a product consumers will pay a premium to own, and a way to refresh an existing model without launching a new one.
St. Andrews Links Trust releases 2025 financial report
St. Andrews Links Trust published its financial results for 2025 with total revenue of $67.05 million (£50.6 million) and a surplus for reinvestment of $11.13 million (£8.4million). The Trust’s seven courses, including the Old Course, welcomed 296,728 rounds last year. Despite seeing surplus decrease from 2024 to 2025, St. Andrews Links Trust saw a 6.8% increase in golfing income due to a modest increase in visitor rounds coupled with a 5% price increase in green fees. Retail (+1.8%) and F&B (+3.3%) saw modest increases while the Trust’s commercial division reported a 5% increase in revenue driven by licensing deals.
Our take: The Home of Golf is a bucket-list destination for millions of golfers around the world. Increasing costs in golf and travel haven’t deterred those from eyeing Ireland. The addition of an eighth course (Craigtoun Course) this year with the Trust taking over the lease on Duke’s Course in January should buoy financials further for 2026
The Fee Is Not the Business
Golf management companies are growing rapidly, but the real opportunity—and risk—lies beyond the management fee, in contract durability, renewal rates and the platform businesses built around the network.
September 28, 2026
Matthew Erley & Evan Roosevelt | Old Tom Capital
Golf's management companies are among the fastest-growing businesses in the game. The National Golf Foundation estimated in 2022 that nearly 2,100 U.S. facilities, more than one in seven, were run by management companies, an increase of more than 18 percent since 2010. Golf Inc. reports that the 11 companies now operating 50 or more courses, a group that includes owner-operators as well as third-party managers, grew their combined portfolios from about 1,165 18-hole equivalents in 2019 to roughly 1,797 in 2026. Cities, private clubs and resort developers increasingly want professional operations without giving up ownership.
The standard way to explain the investment case is to point to Marriott, which separated running hotels from owning them in 1993 and now owns almost none of its rooms. The comparison is intuitive and mostly wrong. Golf managers lack the three things that make hotel fee streams so valuable. What they have instead is an outsourced services business, with a possible platform on top. Investors who can tell those two apart, and who pay only for the part they can verify, will do well in this category. Investors who price the whole thing as Marriott will be paying for a brand that does not exist.
What the Contract Pays
A golf management agreement is simple. The owner keeps the revenue, pays operating costs, funds capital improvements and absorbs losses. The manager receives a base fee and an incentive fee when results clear an agreed hurdle.
Seattle's 2025 agreement with its operator, Premier Golf Centers, is a clean public example. The city pays a $375,000 base fee for four municipal courses, rising 2.5 percent a year, plus 10 percent of revenue above $16.5 million once expenses and the city's debt service are covered. If revenue falls short of that debt service, the operator "shall not under any circumstances be responsible for paying the shortfall." Applied to the roughly $19 million of golf revenue the city reported for 2024, those terms would pay the operator about $625,000 a year. That is roughly 3 percent of revenue, or about $155,000 per course, in line with the 2 to 3 percent base fees common in hotel management.
The fee is paid ahead of the owner's return, and the operator carries no operating loss beyond its incentive fee. That part of the hotel analogy holds. Most of the rest does not.
Why Marriott Is the Wrong Mirror
Marriott is not primarily a hotel manager. Of its $5.44 billion in 2025 gross fees, more than $3.3 billion came from franchising, where the company licenses its brands and reservation system and does little else. Its management contracts with hotel owners generally run 10 to 50 years, according to Host Hotels & Resorts. And its guests choose the brand, which is why owners pay for it.
Golf managers have none of those three things. Few golfers pick a course because of who manages it. There is no franchise business. And contracts are short. Seattle's agreement allows either party to terminate on 50 days' notice. Portland's city code caps golf management agreements at five years. Woodridge, Illinois, hired KemperSports in January 2026 under a two-year professional services agreement, after the prior operator walked away from a 25-year lease more than a decade early. A long stated term that either side can end on 50 days' notice is, economically, a 50-day contract. What remains is the management contract on its own, and the market has priced that business before.
Aimbridge Hospitality, the largest third-party hotel manager, runs hotels for owners without a brand of its own. In January 2025 its first-lien lenders agreed to take majority ownership, converting more than $1.1 billion of its roughly $1.3 billion of debt into equity. The fee income was real. The leverage placed on it assumed a durability the contracts did not provide.
A closer analog sits in parking. SP+ managed parking for cities, airports, hospitals and property owners, and at the end of 2023 ran about 88 percent of its commercial locations under management contracts. Those contracts typically ran one to three years and could be terminated without cause on 30 days' notice or less, much like golf's. SP+ spent years converting leases into management contracts, the same shift now under way in municipal golf, and reported reimbursed site costs as a separate revenue line so investors could see its true fee income. Metropolis Technologies acquired it in 2024 for about $1.5 billion including debt, roughly 11 to 12 times 2023 adjusted EBITDA by our calculation. That is a services multiple, not a hotel-brand one.
The honest valuation range for a golf manager is therefore not somewhere between a course owner and Marriott. It is somewhere between Aimbridge and SP+, with a premium earned only where renewal behavior proves stickier than the contracts require.
What One Contract Is Worth
A simple exercise shows why the distinction matters. Take Seattle's roughly $155,000 per course and assume, for illustration, that a manager keeps half after paying for the regional and corporate teams that serve the contract. That leaves about $78,000 of earnings per course. At the roughly 20 times EBITDA the large hotel companies command, that contract is worth about $1.5 million. At SP+'s multiple, it is worth about $900,000. Private clubs and resorts pay more than municipal courses, so the dollar figures move, but the gap between the two answers does not.
So when a golf manager is valued well above a services multiple, one of two things is true. Either the buyer is paying a franchisor's price for a business without a franchise, or a meaningful share of the earnings comes from somewhere other than the fee. The second possibility is the more interesting one.
Where the Platform Earns
A manager running hundreds of facilities can buy turf products, equipment, food, insurance and software at a scale no single owner can match. It can sell food and beverage, events, instruction and other services into facilities it already runs, operate loyalty programs across its network, and carry practices from one property to the next. In this reading, the management fee is the cost of acquiring the customer. The earnings are in what the platform sells through the relationship once it has it.
That is a hypothesis. The leading golf managers are private and disclose little. But the closest public comparable suggests it is plausible: SP+ told investors it earned operating income on the insurance it provided to clients under its management contracts, buying coverage at rates no single client could get and keeping part of the difference. If golf works the same way, an investor is underwriting not a fee stream but a take rate on a network.
That raises a question every owner eventually asks: who keeps the benefit of scale? Seattle's contract answers it explicitly. The city reimburses operating costs without markup or profit, and only for amounts the operator actually paid to parties unrelated to it. Scale passes through to the owner. Value passed through strengthens the relationship. Only value retained shows up in the manager's earnings. The more a platform depends on the second kind, the more exposed it is when a city auditor or club board asks who captured the purchasing rebate. A buyer should know that split before paying for it.
The Cycle Behind the Incentive Fee
Incentive fees are usually presented as the most attractive feature of the model, and Seattle's numbers show why. Golf revenue at the city's four courses was about $16.7 million in 2022 and $18.8 million in 2023, a 12 percent increase. Under the 2025 agreement's terms, that swing would move the incentive fee from roughly $25,000 to roughly $230,000 against a $375,000 base. A 12 percent change in course revenue produces a roughly ten-fold change in incentive income.
That convexity cuts both ways. Those were the strongest years for golf demand in a generation, and hurdles reset when contracts renew. Seattle's new $16.5 million threshold sits below current revenue and rises 2.5 percent a year. Anyone selling a management business today is marketing incentive income earned near a cyclical high, against hurdles that will be re-struck at the next negotiation. A buyer should underwrite the base fee and treat the incentive fee as option value, not earnings.
The capital cycle points the same way. Winning contracts increasingly requires money up front. Seattle's renewal commits the operator to $100,000 a year toward capital improvements, or $1.5 million over the initial term, and the contract calls it a "Key Money Contribution," borrowing the hotel industry's term. Indian Wells, California, requires its operator to invest $1.25 million of its own money in capital improvements. In hotels, the steady rise of key money has been one of the clearest signs that competition for contracts is moving value from managers to owners. Golf looks early in the same pattern. Meanwhile, leading managers have moved onto the balance sheet; a KemperSports affiliate paid $160 million for Streamsong Resort in 2023. Each step can be rational. Together they describe a business that is less asset-light than its valuation usually assumes.
What Reaches the Manager Anyway
A management contract protects the operator from the owner's losses. It does not protect the operator from the owner's economics. Labor, water and insurance costs land on the owner; golf facilities saw health insurance premiums rise 6.4 percent on their most recent renewal, according to the National Golf Course Owners Association. That pressure moves through the market in three ways.
The first helps managers. Cities with tight budgets and clubs that cannot find experienced leadership turn to outside operators. Some choose leases, under which the operator keeps the revenue and pays rent; Los Angeles County's 2025 lease with American Golf pays the county 30 percent of green fee, cart and range revenue. Others choose management agreements, under which the city keeps revenue and control of pricing and access.
Municipal golf is the largest pool of new contracts. The NGF counts nearly 3,000 municipal courses at more than 2,600 facilities, about 70 percent of them more than 50 years old. Golf Inc., citing a narrower count of roughly 2,700 courses, reports that 18 percent are under third-party management "in some fashion," a measure that may include leases and concessions. That leaves about 2,200 courses without an outside operator. At public fee levels ranging from about $67,000 per course in Great Falls, Montana, to about $155,000 per course in Seattle, those courses represent a hypothetical fee pool of roughly $150 million to $340 million a year. That is meaningful, but it is spread across 2,200 negotiations with public bodies, and a course paying $67,000 may not cover the regional overhead required to serve it. The municipal market is large in facilities and modest in dollars.
The second effect runs the other way. Owners under margin pressure renegotiate base fees, re-tender contracts, ask for larger capital commitments and use short termination rights. Contract count can rise while fee per contract and contract life fall.
The third is structural. Sponsor-backed owner-operators that manage their own facilities are assembling many of the largest private portfolios. The most profitable private contracts are leaving the third-party pool just as the fastest-growing segment, municipal golf, is the lowest-fee and most political.
What a Roll-Up Actually Buys
The National Golf Foundation counts more than 200 management companies outside the largest 15, averaging about five facilities each. They are the natural pool for consolidation, and sponsor interest in the category remains active.
What an acquirer buys in a five-facility operator is a set of relationships, often held by one or two people, under contracts owners can end on short notice. Change of control is the moment owners are most likely to re-tender. The arbitrage between a regional manager bought at a services multiple and a platform valued at something higher exists only if the contracts survive the acquisition.
That makes three numbers decisive, and none appears in a press release. The first is renewal and retention by contract cohort, measured through at least one change of ownership; SP+ reported 94 percent location retention for 2023, a useful reference from another management-contract industry. The second is capital committed per dollar of annual fee. The third is the share of reported revenue that is fee income rather than reimbursed site cost. In 2023 SP+ reported $883 million of services revenue and a further $899 million of reimbursed management contract revenue, so the same business could look roughly twice as large, at roughly half the margin, depending on presentation.
Our View
Golf management is a good business that is easy to overpay for. The fee is senior to the owner and needs little capital. It is also short-dated, increasingly competed for, and exposed to the same cost pressures that push owners to outsource in the first place. On its own, it is worth a services multiple, and the market has already shown what happens when it is levered like something more.
The value in this category sits in two places the fee does not capture. The first is renewal: owners who keep saying yes through a downturn, a hurdle reset and a change of ownership. The second is retained platform earnings: purchasing, services and programs the manager keeps rather than passes through. Neither shows up in a contract, and both can be verified only in diligence.
That is the opportunity we see. The winners will not be the investors who buy the most contracts. They will be the ones who treat the fee as the price of admission, prove renewal before they pay for it, and pay a premium only for platform earnings they can see in the numbers. The fee is not the business. What the fee makes possible is.
Source Note:
National Golf Foundation, "An Update on the Golf Management Space," September 1, 2022; "The Quiet Growth of Municipal Golf," July 2, 2026.
Golf Inc., "Largest Golf Management Companies Grow 54% Since 2019," July 1, 2026; "Municipal Golf Is Starting to See the Benefits of Third-Party Management," September 3, 2026; "Streamsong Resort Sells for $160 Million to KemperSports Subsidiary," January 2023.
City of Seattle, Ordinance 127243 and golf course management agreement with Premier Golf Centers, July 2025; Premier Golf Centers, 2023 Annual Report to Seattle Parks and Recreation; Seattle City Council, Parks, Public Utilities and Technology Committee briefing, June 11, 2025.
City of Portland, City Council Report 894-2022, and City Code 5.68.020.
KemperSports, "KemperSports Selected to Manage Village Greens of Woodridge," January 13, 2026; Woodridge Park District, lease termination announcement, August 2025.
City of Indian Wells, Indian Wells Facts, Indian Wells Golf Resort.
City of Great Falls, Montana, golf management agreement extension with CourseCo, as reported by The Electric, April 2026.
Los Angeles County Board of Supervisors, Board Letter and Lease Agreement for El Cariso, Victoria and Lakewood golf courses, September 9, 2025.
Marriott International, Fourth Quarter and Full Year 2025 Results, February 10, 2026.
Host Hotels & Resorts, Form 10-K for fiscal 2024 and fiscal 2025, notes on hotel management agreements.
Aimbridge Hospitality, restructuring support agreement announcement, January 16, 2025.
Metropolis Technologies, "Metropolis Technologies, Inc. to Acquire SP Plus Corporation for $1.5 Billion," October 5, 2023, and closing announcement, May 2024; SP Plus Corporation, Fourth Quarter and Full-Year 2023 Results, February 27, 2024; SP Plus Corporation, Form 10-K for fiscal 2023.
National Golf Course Owners Association, 2026 Golf Industry Compensation & Benefits Report, February 2026.
Hotel company EBITDA multiples, the SP+ transaction multiple, Seattle fee estimates and per-contract valuations are OTC calculations and illustrations, not reported data.

One last thing... Jimmy Roberts
Works Like A Charm
Essay originally published in The Met Golfer, September 2013. Special thanks to the Metropolitan Golf Association.
“When I was 12 years old,” says the now 69-year-old Avezzano, “my mother chased me out of the house to caddie here.”
According to the U.S. Bureau of Labor Statistics, these days the typical American stays in a job for just a bit more than four years. “Hard to believe,” says Tom Avezzano. “Sometimes it takes longer than that to get comfortable or get trained.” You have to understand Avezzano’s frame of reference. For the last 38 years, he’s had one job: head professional at the Sprain Lake Golf Course in Yonkers, N.Y. He is the longest-serving pro at one facility in the Met Area, but that only scratches the surface of his loyalty to the place and to the game.
- That was 1956.
- He got four dollars a loop.
- He navigated the six miles mostly hitchhiking down Sprain Road.
- He gave all the money to his mom.
- A year later, Sprain’s head pro, John Frucco, asked Avezzano if he’d come work for him in the golf shop.
And so it started. First, there were 19 years behind the counter during which he became an assistant. Then, in 1975, he took over as the head pro himself. “It’s funny,” he says. “I was the youngest pro in the section. Now I think I might be the oldest.”
Avezzano is a throwback to a time when people grew up, got a job in their hometown, and never left—not because they couldn’t, but because they didn’t want to. “I was approached a couple of times over the years about other jobs,” he says. “One at Westchester Hills and one at Siwanoy, but working at a private club is just a different deal. You have 200 bosses. Here, all I’ve had to deal with is the changing politics of county government.”
Avezzano still lives in Yonkers with his wife of 45 years, his high-school sweetheart. He’s not an easy man to get a hold of, unless you’re willing to venture out to Sprain’s range, where he spends most all his days, giving lesson after lesson.
- “When you love what it is that you’re doing,” Avezzano says, “you don’t work a day in your life. That’s me.”
- And so he’s at it seven days a week in season, from as early as 4:00 a.m. on weekends to 6:00 or 7:00 at night, his only indulgence his own Friday morning game with a few buddies at various area courses.
- “If he had two or three days off in a row, I don’t think he’d know what to do,” says his elder son, Thomas Jr., 41.
The Avezzanos—Thomas Sr., Thomas Jr. and younger brother Michael—now run not only the golf operation at Sprain but also at Maple Moor Golf Course in White Plains, N.Y. “I know a lot of families can’t work together,” says Thomas Jr., “but I couldn’t have a better role model. For Dad, it’s always been about the customers. Make them happy. The golf course is supposed to be a place you come for happy time.”
“I always want to make people feel like this is their golf course,” Thomas Sr. says. “I don’t know how I did it. I’ve been here 56 years. I don’t feel like I’m even 56 years old!”
Past Briefs
Monthly and Annual Membership Options Available.
Member Pricing
$9.99 per month, OR $99 for one year.
Cancel Anytime.
Available for a limited time only, subscribe to our twice-weekly Golf Business Intelligence Brief for a discounted rate of $9.99/month or $99/year. Subscription renews at the same price each month or year, depending on the subscription selected.
Purchase Disclosure
By completing your purchase, you agree to enroll in a monthly or annual subscription to The Big Swing Golf Business Intelligence Brief at the current rate of $9.99 a month or $99 a year.Your subscription will automatically renew monthly at $9.99 or annually at $99 unless canceled prior to the renewal date.
You may cancel at any time through your account settings or by contacting customer support. All sales are final and non-refundable except where required by law.
Offer valid for a limited time and may not be combined with other promotions. Limit one per customer.
By subscribing, you agree to our Terms of Service and Subscription Terms.